What Is Workers’ Compensation Insurance?
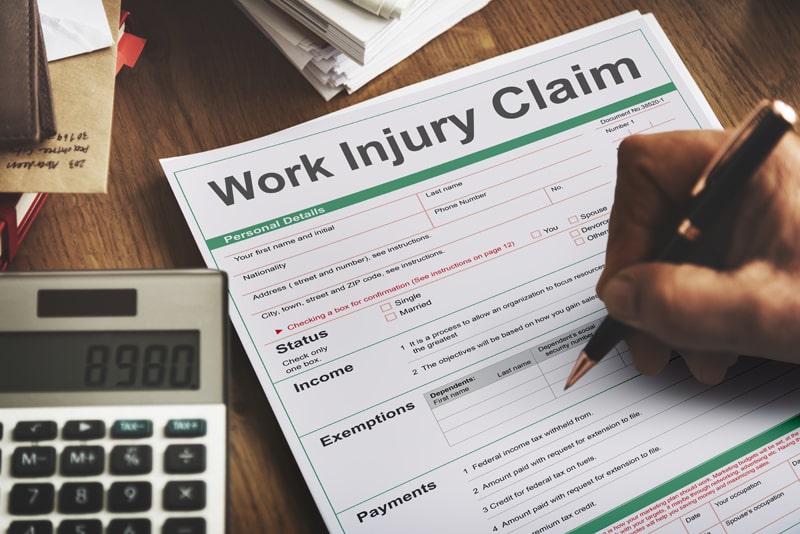
Workers’ compensation insurance — often called “workers’ comp” — is a type of business insurance that helps protect both employees and employers when a work-related injury or illness happens.
In simple terms, if an employee gets hurt on the job (say, falling off a ladder or straining their back while lifting), this coverage helps pay for:
- medical expenses,
- lost wages during recovery,
- and long-term disability or rehab if needed.
For employers, it means protection from lawsuits. In general, workers’ compensation is the exclusive remedy for work-related injuries, meaning employees generally cannot bring a civil lawsuit against their employer for those injuries.
Bottom line? Workers’ comp keeps your business and your team safe when accidents happen.
What Does Workers’ Comp Insurance Cover?
Workers’ compensation insurance is designed to take care of the real costs that come with workplace injuries or illnesses. Here's what’s typically included in your coverage:
Medical Expenses
From doctor visits to surgeries, X-rays, medications, and physical therapy — workers’ comp helps cover it all so your employee can get proper treatment without delay.
Lost Wages
If an employee needs time off to recover, workers’ comp provides temporary disability benefits that partially replace lost wages when an employee is unable to work because of a work-related injury or illness. This gives them time to heal while still getting some financial support.
Ongoing Care
Some injuries need long-term treatment, like rehabilitation or specialist care. Workers’ comp steps in to help with these costs.
Disability Benefits
Whether temporary or permanent, partial or total — if an injury limits an employee’s ability to work, the policy helps cover disability payments.
Death Benefits & Funeral Costs
In tragic cases where a work-related incident leads to death, the policy provides financial support to the worker’s family.
Workers’ compensation generally applies to injuries and illnesses arising out of and occurring in the course of employment. Certain claims may be subject to exclusions, defenses, or limitations under applicable law.
Who Needs Workers’ Compensation Insurance?
If you have employees, you may be required to carry workers’ compensation insurance. Requirements vary by state and by the type of workers you employ. Here's a breakdown of who needs it:
Small Business Owners
Whether you run a café, a fitness studio, or a local store, if you have staff, you need coverage. Even part-time employees count in most states.
Contractors & Subcontractors
Independent contractors often aren’t covered under a business’s workers’ comp policy, but depending on the state, you might still be responsible for their coverage if they’re working for you.
High-Risk Industries
Construction, manufacturing, warehousing, and transportation are just a few industries where injuries are more likely — and where workers’ comp is especially crucial.
Office-Based Businesses
Don’t assume a desk job means no risk. Slips, repetitive strain injuries, or even accidents during company events can all lead to claims.
In California, employers are generally required to carry workers’ compensation insurance even if they have only one employee. The penalties for not complying can be steep — including fines or business shutdowns.
How Much Does Workers’ Compensation Insurance Cost?
The cost of workers’ comp insurance depends on a few key factors — but don’t worry, we’ll break it down simply:
1. Payroll Size
The more employees you have (and the higher their wages), the more you’ll pay. That’s because premiums are based on total payroll.
2. Type of Work
Each job has a risk rating. Office admin? Low risk. Roofing? High risk. The riskier the job, the higher the premium. Makes sense, right?
3. Claim History
Your claims history can affect your workers’ compensation premium. A history of frequent or serious injuries? That can bump your rates up.
4. Location
Rates vary by state. For example, workers’ comp insurance in California tends to be higher than in some other states due to strict regulations and cost of care.